 Bad news
Moderna's Profit Rests on COVID Shots and Cuts as Nine-Month Loss Hits $1.96 Billion
Moderna's $162 million third-quarter profit followed a cut in research spending and came from COVID-19 vaccine sales abroad. The company is still $1.96 billion in loss for nine months, with unpaid sales up sharply and a norovirus trial short of its early target.
Read the good side of this story
Moderna Posts Its First Quarterly Profit in Years as Revenue Jumps 29%
Moderna’s first quarterly profit in years comes with a loss for the year attached. The company reported net income of $162 million for July to September. Its net loss for the first nine months of 2026 is $1.96 billion, almost the same as the $2.0 billion loss at this point in 2025. One good quarter has not changed the shape of the year.
The release also shows how the profit was made. Research and development spending fell from $801 million to $583 million, a cut of $218 million in a company whose pitch is its pipeline. Revenue rose 29% to $1.31 billion, well above the $885 million analysts expected, CNBC reported. The growth came mostly from higher overseas sales of the COVID-19 vaccine, including Canada, the United Kingdom and Asia.
One product still carries the company
Moderna reports $780 million of revenue in the United States and $533 million abroad, but it does not break out sales by product. That leaves outsiders unable to see how much the newer vaccines contributed. Chief executive Stéphane Bancel credited new products and a wider spread of customers, yet the figures that would test that claim are not in the release.
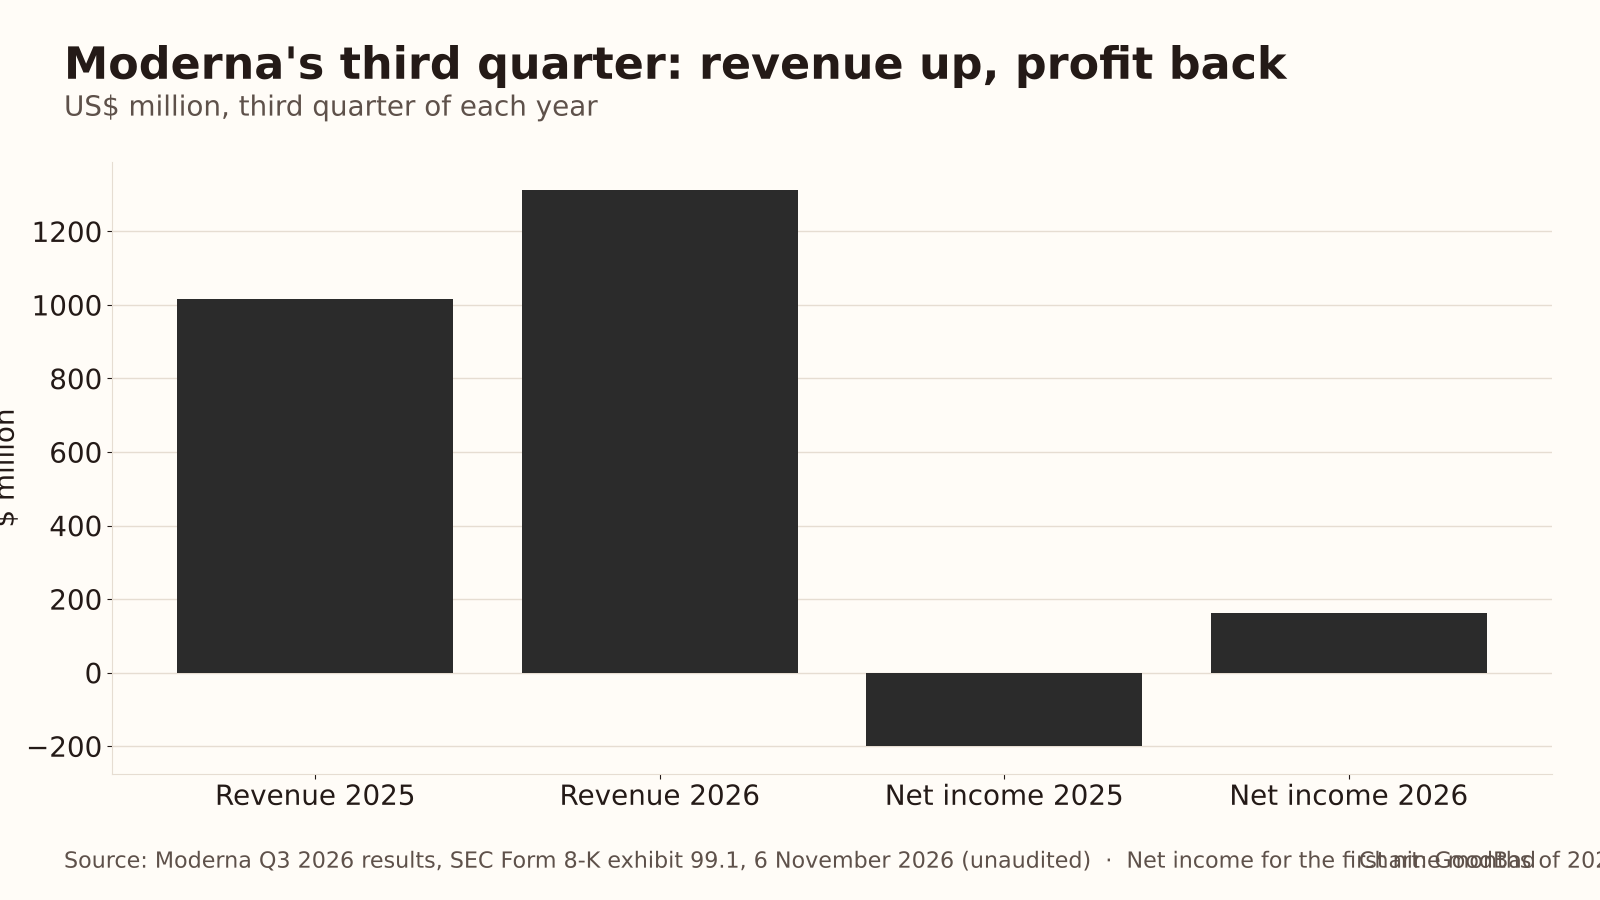 Chart: GoodBad. Data from Moderna’s third-quarter 2026 results (unaudited), SEC Form 8-K, 6 November 2026.
Cost of sales rose from $207 million to $318 million, and it includes $65 million of third-party royalties. For the full year the company expects a cost of sales of about $1.7 billion, which includes a $0.9 billion non-recurring litigation charge. A $950 million litigation payment went out in the quarter, and a patent dispute with GSK was settled on 28 October.
Cash that is borrowed or not yet collected
Moderna holds about $8.0 billion in cash and investments, up from $6.9 billion at the end of June. The release attributes the rise mainly to about $2.6 billion in net proceeds from convertible notes, partly offset by the $950 million payment. That is borrowing, not earnings. Operating cash outflow for the nine months was $2.7 billion.
Receivables, the money customers owe for products already delivered, rose to $1.37 billion from $184 million at the end of 2025, and the release attributes this largely to uncollected third-quarter sales. A profit that has not yet been paid for is a weaker profit. The financial statements are unaudited, and the company gives no date for cash breakeven.
Pipeline gaps
The pipeline had a setback. An interim Phase 3 analysis of Moderna’s norovirus vaccine, mRNA-1403, did not meet the early-success criteria, so no further group of volunteers will be enrolled this season. The company is awaiting pivotal data in 2026 for a treatment for propionic acidemia, a rare metabolic disease.
There is good news in the release, and we set it out in the companion piece. The melanoma vaccine intismeran, combined with Merck’s Keytruda, cut the risk of recurrence or death by 42% in a Phase 3 trial. The FDA approved the flu vaccine mFLUSIVA for adults 50 to 64 in August, with accelerated approval for those 65 and over. Regulatory submissions for the cancer vaccine are still being prepared, so no patient outside a trial can have it yet.
The test ahead
Moderna now guides to 15% to 25% revenue growth for 2026, up from a previous forecast of up to 10%. CNBC says the stock is up more than 700% this year, largely on hopes for the cancer vaccine, which means the share price already reflects a good deal of success. The quarter’s profit, the company’s own figures show, came from overseas COVID-19 sales, lower research spending and sales not yet collected.